4

Let $X$ and $Y$ be two non independent random variables. Suppose to generate $n$ realizations of both variables, and indicate with $(X_i, Y_i)$ their values. Also, let's pose that $X$ and $Y$ are non independent only within a particular realization; in other words, any realization does not affect the result of the others.

What can I do to find a statistical unbiased estimator of central moments $$m_{a,b} = \mathbb{E}[(X-\mu_x)^a(Y-\mu_y)^b]$$ which uses the $n$ realizations $(X_i, Y_i)$ except from doing by hand all calculations for each $a$ and $b$? Is there some readings I'm missing?

Some additions

First of all, I forgot to write these: $$\mu_X = \mathbb{E}[X], \mu_Y = \mathbb{E}[Y]$$

the_candyman
  • 14,292

1 Answers1

3

You seek the bivariate h-statistic $h_{r, t}$ defined by:

$$E[h_{r, t}] = \mu _{r,t} $$

That is, $h_{r, t}$ is the statistic whose expectation is the bivariate central moment:

$$\mu _{r,t} = E\left[(X-E[X])^r (Y-E[Y])^t\right]$$

Unfortunately, deriving h-statistics by hand is extremely complicated and prone to error, and they are best obtained by computer algorithm, such as the HStatistic function in the mathStatica package (I should add I am an author of the latter). In fact, much of the published literature in this field contain errors, in some cases remaining uncorrected for 50 or more years.

To illustrate, an unbiased estimator of the bivariate central moment $\mu _{3,1}$ is the bivariate h-statistic $h_{3,1}$:
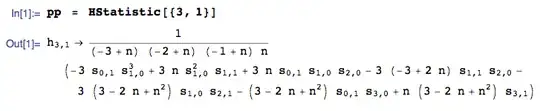
enter image description here

where the solution is expressed in terms of bivariate power sums:

$$s_{a, b}=\sum _{i=1}^n X_i^a Y_i^b $$

which you can then compute given your $(X_i, Y_i)$ data. All done.


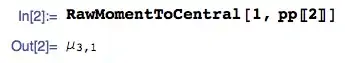
To verify that pp above is, in fact, an unbiased estimator, compute $E[$[pp], which is just the 1st RawMoment of pp (and express the solution in terms of CentralMoments):
enter image description here


For more detail

For more detail, see, for instance, Chapter 7 of our book, "Mathematical Statistics with Mathematica". A free download of the chapter is now available here:

http://www.mathStatica.com/book/Rose_and_Smith_2002edition_Chapter7.pdf

Subsequent editions extend from univariate h-statistics to the multivariate case.


OP wrote:

By the way, I need to have unbiased estimator for $h_{1,2}$, $h_{1,1}$, $h_{2,1}$ ...

No problem ...
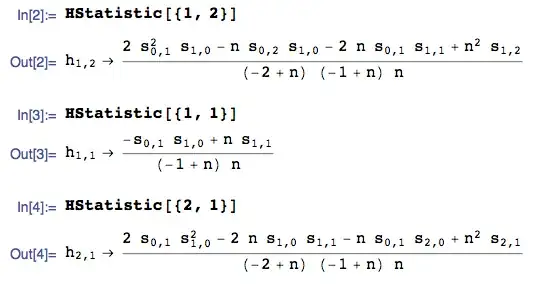
enter image description here

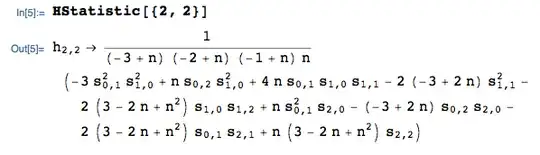
And @Ivan seeks $h_{2,2}$:

enter image description here

wolfies
  • 5,254
  • thank you! is there something similar for Matlab? – the_candyman Nov 22 '13 at 08:44
  • Not sure, but it seems unlikely ... the methods require sophisticated computer algebra techniques, so Maple would be more likely than Matlab. If you have a particular 'h-statistic' you are seeking to evaluate, please let me know which one and I would be happy to post the solution here for you. – wolfies Nov 22 '13 at 10:15
  • Thank you for your kindness! I'm looking around on google but I don't find anything for matlab. By the way, I need to have unbiased estimator for $h_{1,2}$, $h_{1,1}$ and $h_{2,1}$. – the_candyman Nov 22 '13 at 14:12
  • @the_candyman No problem - easy cases :) Please see results added above – wolfies Nov 22 '13 at 14:34
  • one thousand times... THANK YOU!!! :D – the_candyman Nov 22 '13 at 14:45
  • @wolfies Oh my god I've been looking for this for ages. I just need the $h_{2,2}$ as well. Could you post it? – Ivan May 16 '18 at 18:36
  • 1
    @Ivan added $h_{2,2}$ for you :) – wolfies May 16 '18 at 20:05
  • @wolfies Thank you so very much! – Ivan May 17 '18 at 16:55
  • @wolfies Hello again! I just want to know if multivariate Polyaches are implemented in the current version of mathStatica. – Ivan May 22 '18 at 16:22
  • @Ivan Yes. The Polyaches are defined as an unbiased estimator of the product of central moments, and works for both univariate and multivariate cases. An unbiased estimator of the product of $\mu_{1,1,2}$ and $\mu_{2,2,3}$ is given by: PolyH[{ {1, 1, 2}, {2, 2, 3} }] – wolfies May 22 '18 at 19:17